 Whatsapp
Corporate Treasury Centres in GIFT IFSC: Registration, Permitted Activities and the Deemed-Dividend Question
A group treasury centre helps multinational groups manage funds and lending between affiliates. In GIFT IFSC, a Global or Regional Corporate Treasury Centre (GRCTC) operates under
Relocating an Offshore Fund to GIFT IFSC : The Tax-Neutrality Conditions
Moving a fund is not like moving an office. The relocation of offshore funds to GIFT City can involve two potential capital gains tax events: the fund’s transfer of assets to a n
Twenty Years, Not Ten: GIFT City Tax Holiday Under Section 147 After the Finance Act, 2026
The phrase “GIFT City tax holiday” conceals three legal questions that decide whether anything is actually exempt: which entity qualifies, which income qualifies, and f
Inside India, Outside for FEMA: The Legal Status of a GIFT IFSC Unit
A company incorporated in GIFT IFSC is an Indian company. For foreign exchange purposes, however, it is treated as a person resident outside India. It also sits within a Special Ec
Liquidated Damages under Section 74 of the Contract Act: Does a Claimant Still Have to Prove Loss?
Commercial contracts routinely include a liquidated damages clause that fixes a sum payable for breach, such as a specified amount for each week of delay or a percentage of the con
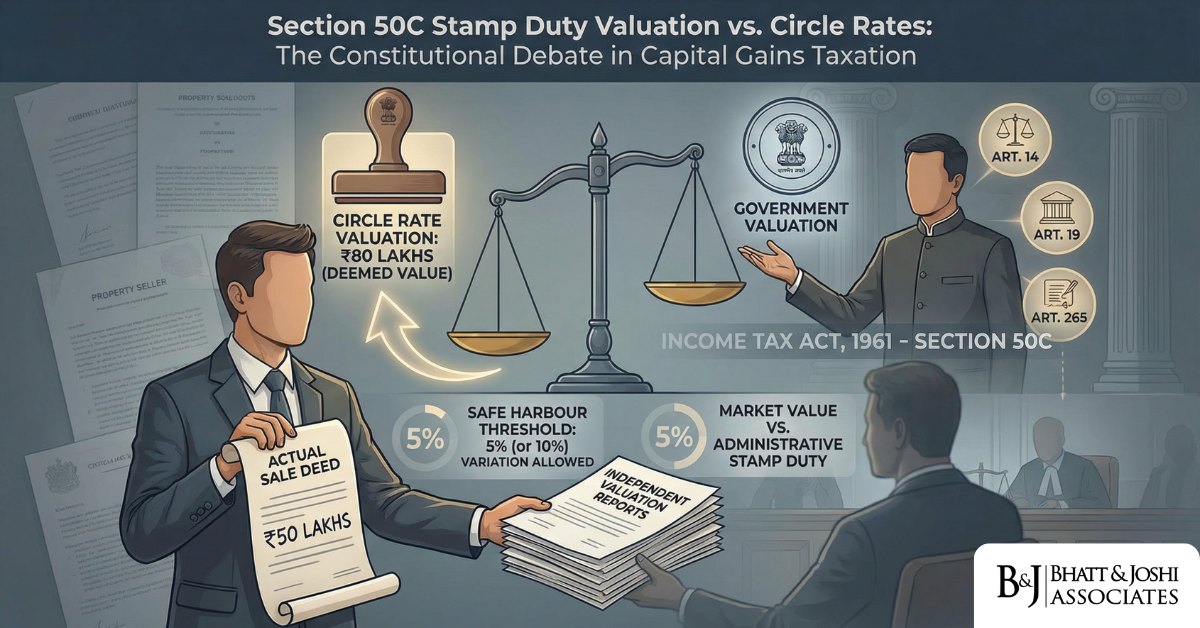
Section 50C of the Income Tax Act, 1961 Stamp Duty Valuation vs. Circle Rates: The Constitutional Validity of Deeming Fictions in Capital Gains
Introduction Few provisions in Indian income tax law generate as much sustained controversy, litigation, and legislative amendment as Section 50C of the Income Tax Act, 1961. At it
Startup Losses and Section 79 of the Income Tax Act, 1961: When Anti-Abuse Rules Kill Legitimate Restructuring
Introduction India’s startup ecosystem has grown into one of the most dynamic in the world, yet founders and investors continue to grapple with a tax provision that was never
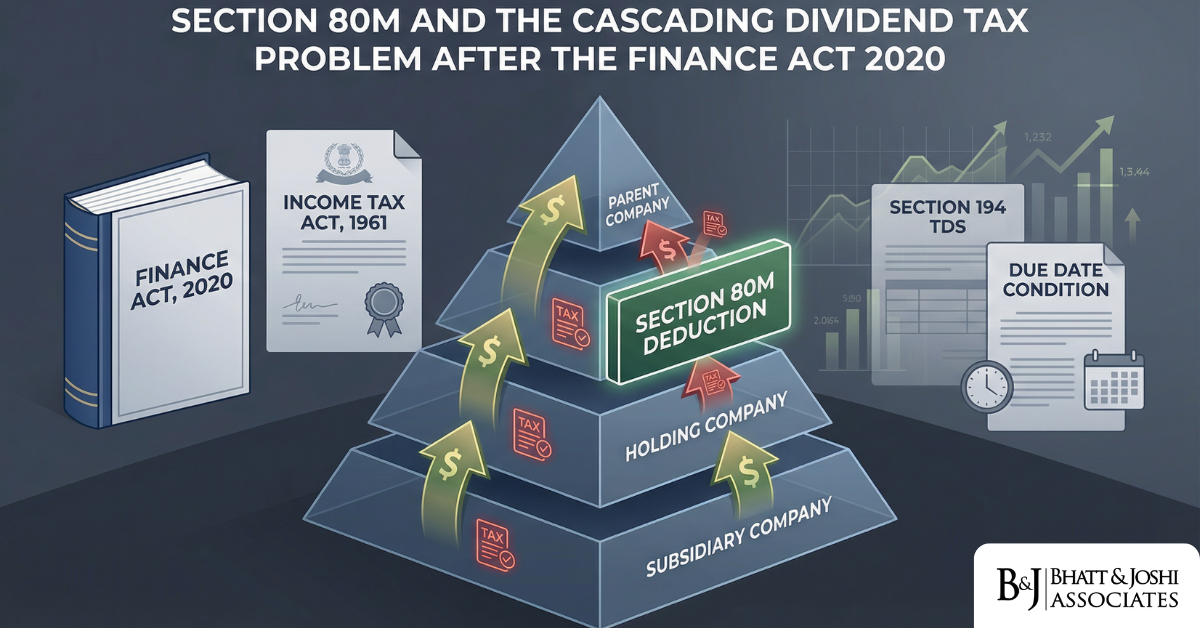
Section 80M Income Tax Act: Inter-Corporate Dividend Deduction
Introduction When the Finance Act 2020 abolished the Dividend Distribution Tax (DDT) under Section 115-O of the Income Tax Act, 1961, India shifted from a company-level tax to the
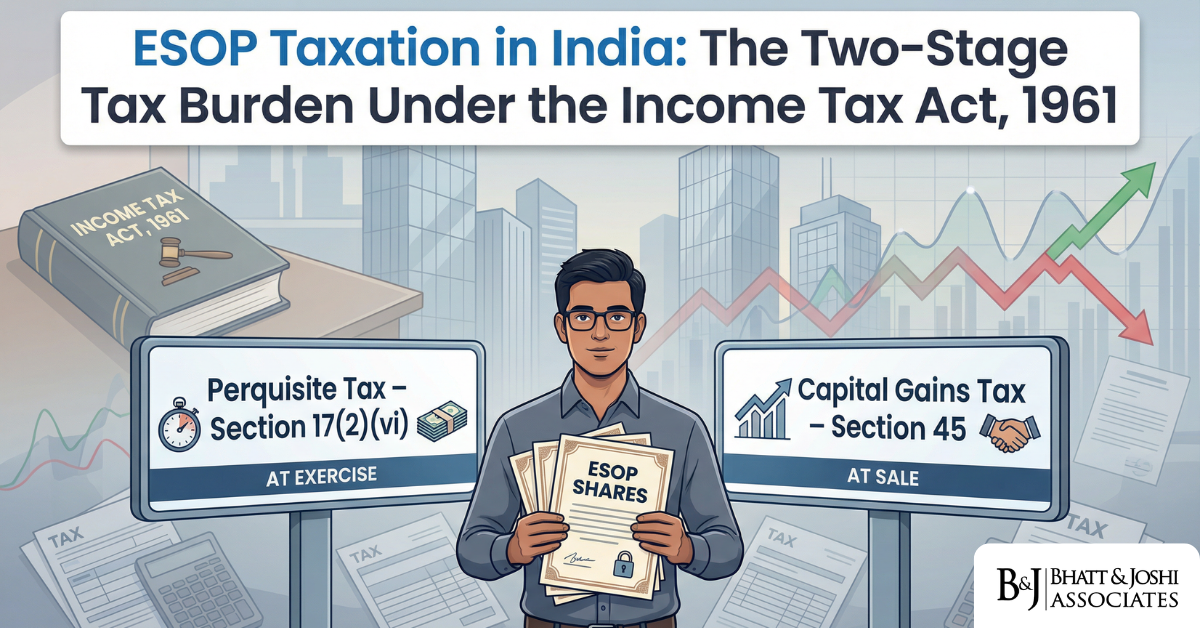
ESOP Taxation After Exit: Why Perquisite Tax at Exercise and Capital Gains at Sale Creates Double Taxation by Stealth
Introduction Employee Stock Option Plans (ESOPs) are among the most powerful instruments that Indian startups and companies use to attract, retain, and motivate talent. ESOPs give
Fractional Ownership of Real Estate and Income Tax: How Co-Ownership Platforms Fall Through the Cracks of Section 54 and 54F
Introduction Fractional ownership of real estate has moved from a niche arrangement between family members and business partners to a fully commercialised, technology-enabled inves