 Whatsapp
Rejection of Books under Section 145(3) and Best-Judgment Assessment under Section 144: When May the Taxman Set Aside Your Accounts, and What May He Put in Their Place?
Imagine a trader in semi-precious stones who has maintained a cash book, purchase register and sales ledger for years, had his accounts audited, and filed a return showing a modest
IBC “Clean Slate” Principle: Extinguishment of Tax Dues on Approval of a Resolution Plan
The question goes to the heart of what an insolvency resolution is for. If old, unquantified liabilities can reappear after the plan is signed, no rational investor will pay a fair
Penalty for Concealment and Inaccurate Particulars: Section 271(1)(c), Section 270A, and the Road to the 2025 Act
A Deduction That Failed, And A Penalty That Followed Consider a manufacturing company that borrows money from its bankers and uses part of it to subscribe to shares in a group conc
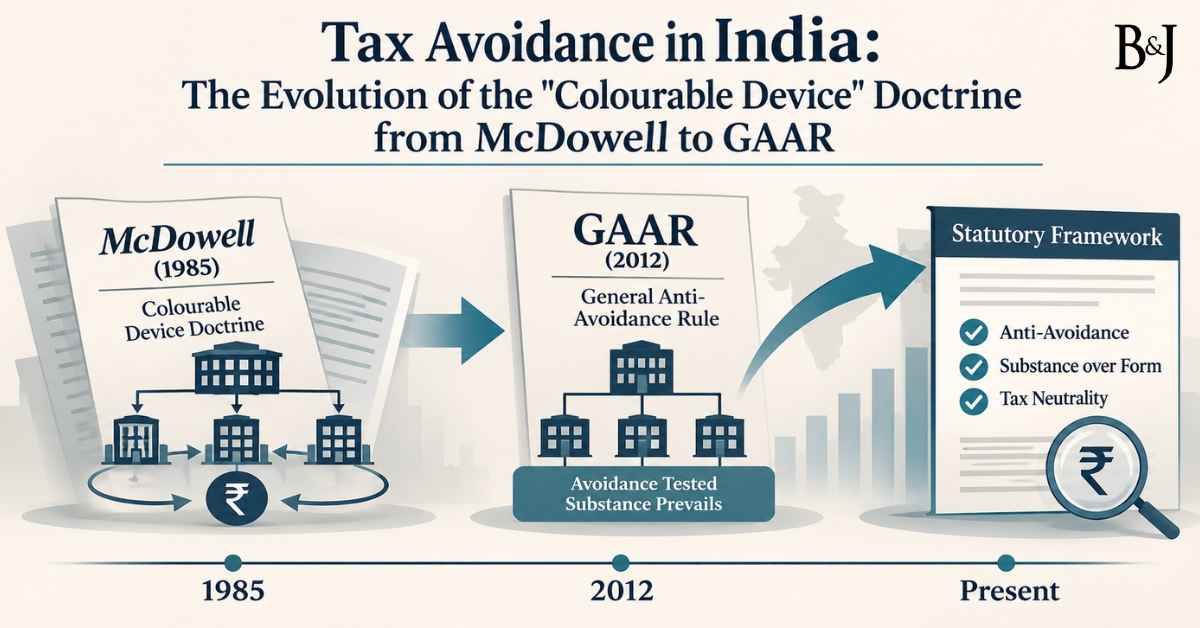
Tax Avoidance in India: The Evolution of the “Colourable Device” Doctrine from McDowell to GAAR
One sentence from a 1985 sales-tax judgment has been cited in Indian tax litigation more often than almost any other. This is what it actually says. A promoter holds shares in a cl
Minimum Alternate Tax under Section 115JB: How Far May the Assessing Officer Recast Book Profit?
An Illustration Imagine a manufacturing company that reports, in its audited accounts, a profit of Rs 100 crore. Because of generous depreciation, a tax holiday and brought-forward
Indexation on Inherited Property and Dissolved Firms: Whose Clock Counts?
Consider two quite different taxpayers. The first is a woman who inherits a plot of land from her father, who bought it in 1998, and who sells it in 2012. She is told by the Assess
Section 43CB of Income Tax Act and ICDS: When Is a Builder’s Income Taxable?
How ICDS, section 43CB and the courts decide when a builder’s income accrues – percentage of completion, project completion and development rights. Consider a developer
Capital Gains on Self-Generated Goodwill: Section 55 and the Machinery Provision
B.C. Srinivasa Setty, PNB Finance and the section 55 machinery: when a self-generated intangible escapes capital gains, and when it no longer does. Sections 45, 48, 50D and 55 of t
Book Entries and Income Tax: When Accounting Treatment Does Not Decide Tax Liability
A proposition that cuts both ways, an exception where Parliament has reversed it, and the awkward case of the scheme sanctioned by a court. This raises a fundamental question in in
Speculation Loss and the Explanation to Section 73: Trading in Shares and Commodities
An Illustration Consider a private company whose main line of business is manufacturing and selling industrial goods. In a year of good manufacturing profits, its treasury desk als