 Whatsapp
Minimum Alternate Tax under Section 115JB: How Far May the Assessing Officer Recast Book Profit?
An Illustration Imagine a manufacturing company that reports, in its audited accounts, a profit of Rs 100 crore. Because of generous depreciation, a tax holiday and brought-forward
Book Entries and Income Tax: When Accounting Treatment Does Not Decide Tax Liability
A proposition that cuts both ways, an exception where Parliament has reversed it, and the awkward case of the scheme sanctioned by a court. This raises a fundamental question in in
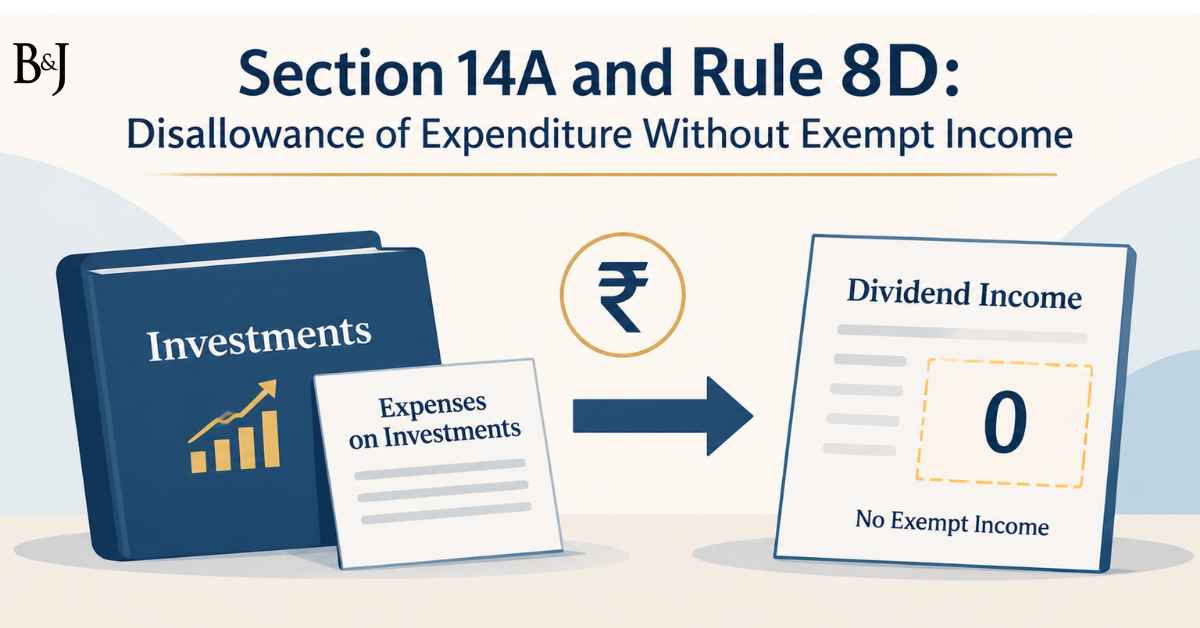
Section 14A and Rule 8D: Disallowing Expenditure When There Is No Exempt Income
Consider a manufacturing company that, over several years, has bought shares in two of its group companies. It holds them to retain control of the group, not for trading. It borrow
Section 14A/Mat Disallowances: Section 14A Disallowance: A Comprehensive Assessee Defense Strategy Across DRP, CIT(A), and ITAT
1. INTRODUCTION: THE ASSESSEE’S STRATEGIC LANDSCAPE Understanding the Asymmetry The relationship between the tax department and the assessee is inherently asymmetrical. The D
Section 115JB MAT vs Section 14A Rule 8D: Why Accounting Standards Prevail Over Tax Formulas
1. INTRODUCTION: THE CONCEPTUAL CLASH The Fundamental Tension At the heart of the Section 14A Rule 8D vs. Section 115JB debate lies a profound conceptual clash: On one side: The
Explanation 1 to Section 115JB – A Clause-By-Clause Analysis Of Book Profit Adjustments
1. INTRODUCTION: THE ARCHITECTURE OF BOOK PROFIT What is Explanation 1? Explanation 1 to Section 115JB(2) is the rulebook for computing book profit. It specifies, with surgical pre
MAT Book Profit vs Taxable Income: Section 115JB IT Act Guide
1. INTRODUCTION: THE TWIN TAX PROBLEM The Scenario That Started It All Imagine it’s the year 1997. You’re a wealthy Indian businessman running a successful manufacturin
Section 14A in MAT (Section 115JB): Can Rule 8d Disallowances Inflate Book Profits?
1. The Core Contradiction: Section 14A vs Section 115JB MAT The Core Contradiction Imagine this scenario: Company ABC Ltd. for AY 2023-24: Under Section 14A (Normal Computat