 Whatsapp
IBC “Clean Slate” Principle: Extinguishment of Tax Dues on Approval of a Resolution Plan
The question goes to the heart of what an insolvency resolution is for. If old, unquantified liabilities can reappear after the plan is signed, no rational investor will pay a fair
Penalty for Concealment and Inaccurate Particulars: Section 271(1)(c), Section 270A, and the Road to the 2025 Act
A Deduction That Failed, And A Penalty That Followed Consider a manufacturing company that borrows money from its bankers and uses part of it to subscribe to shares in a group conc
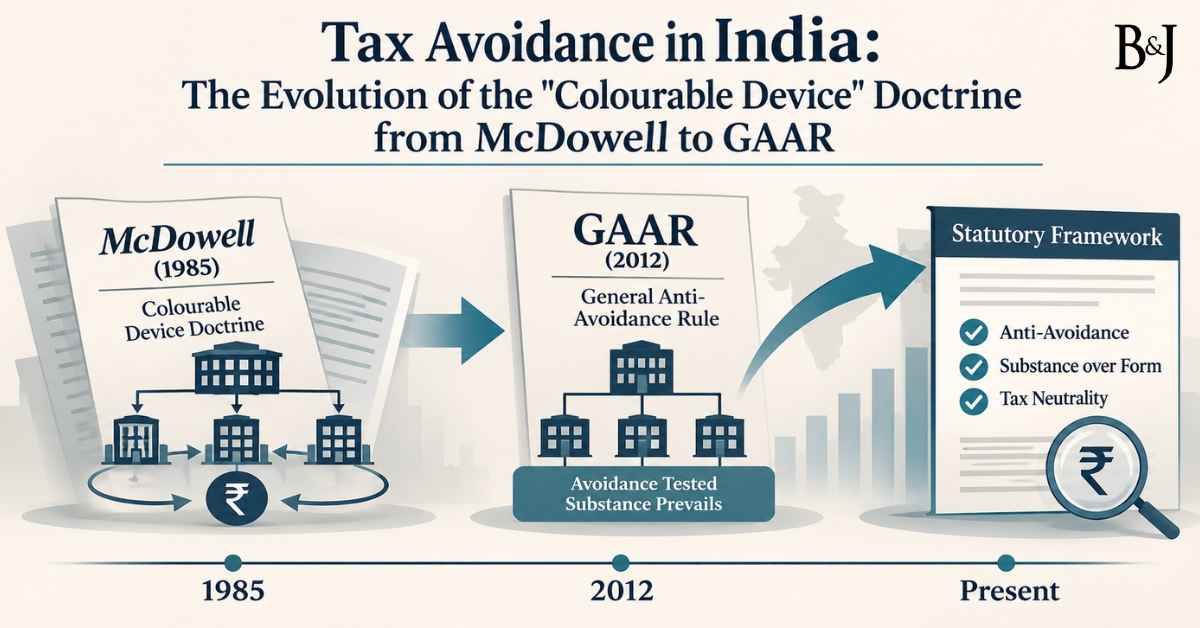
Tax Avoidance in India: The Evolution of the “Colourable Device” Doctrine from McDowell to GAAR
One sentence from a 1985 sales-tax judgment has been cited in Indian tax litigation more often than almost any other. This is what it actually says. A promoter holds shares in a cl
Minimum Alternate Tax under Section 115JB: How Far May the Assessing Officer Recast Book Profit?
An Illustration Imagine a manufacturing company that reports, in its audited accounts, a profit of Rs 100 crore. Because of generous depreciation, a tax holiday and brought-forward
Book Entries and Income Tax: When Accounting Treatment Does Not Decide Tax Liability
A proposition that cuts both ways, an exception where Parliament has reversed it, and the awkward case of the scheme sanctioned by a court. This raises a fundamental question in in
Section 14A and Rule 8D: Disallowing Expenditure When There Is No Exempt Income
Consider a manufacturing company that, over several years, has bought shares in two of its group companies. It holds them to retain control of the group, not for trading. It borrow
Section 80-IA Deduction: Which Profits Qualify and Which Expenses Count?
Sections 80-IA, 80-IB and 80-IC of the Income-tax Act, 1961, and their successors in the Income-tax Act, 2025 A Unit, A Subsidy And A Head Office Consider a manufacturer with two f
Developer or Works Contractor? Section 80-IA(4) and the Line the Explanation Draws
A Canal, A Company, And A Hundred Crores Of Doubt Consider a construction company – call it Saraswati Infra – which wins a tender floated by a State irrigation departme
Revision under Section 263: “Erroneous and Prejudicial” and the Problem of Enquiry
A power to correct an officer’s mistakes, or a second opinion on his judgment? Fifty years of case law on a single conjunction. A partnership firm files its return. The Asses
Validity of Notice: Section 143(2), Section 292BB and Curable Defects
Imagine a trader who files her return in good time and is later invited to a hearing. Questionnaires arrive, she replies, her accountant attends, and an assessment order follows wi